The United States and its Western allies are finally waking up to a stark reality: global supply chains for critical minerals are deeply vulnerable, and decades of strategic complacency have left advanced democracies at the mercy of Beijing. Over the past thirty years, China has systematically established a dominant share of global mineral production. The sporadic export controls introduced by Beijing since 2023 have served as a wake-up call, demonstrating precisely how perilous it is for other nations to rely entirely on China for the raw materials that form the indispensable backbone of modern semiconductors, advanced defense technologies, and the booming automotive sector.
In response, Washington and various European capitals are scrambling to minimize their exposure. Working alongside private firms, these Western governments have begun funneling capital into both upstream industries—including mines, refineries, and recycling infrastructure—and downstream manufacturing sectors like magnets and batteries. So far, the vast majority of these public and private efforts have concentrated on mines that are already operational or very close to it, alongside a heavy emphasis on building up domestic and allied processing and refining capabilities. Policymakers frequently point out that the United States and Europe currently lack sufficient facilities to process raw ore into specialized chemicals or refined materials. Expanding refining capacity is undeniably necessary to reduce immediate reliance on China and alleviate short-term supply chain anxieties.
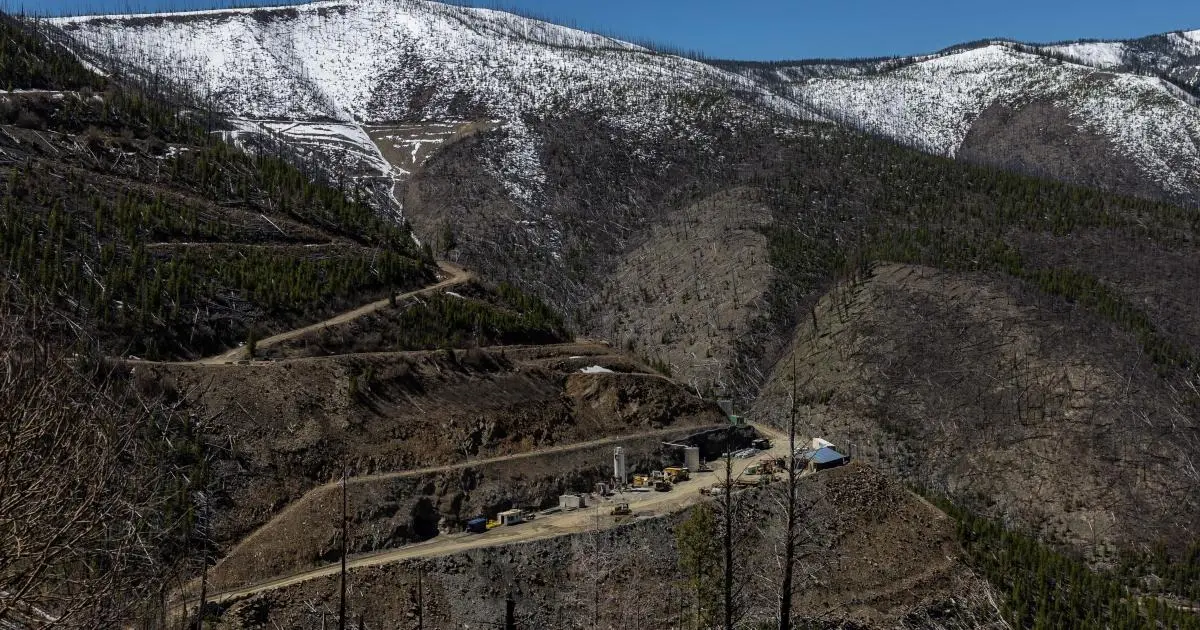
Yet, experts warn that this strategy is merely a temporary fix. Refining facilities are ultimately useless unless they are fed by a steady, long-term supply of raw materials. Securing that continuous feed requires the development of entirely new mines, a particularly urgent imperative as advanced industries demand ever-higher volumes of specialized minerals. Because the arduous process of discovering, permitting, and building a modern mine takes roughly two decades, ensuring a secure long-term supply of minerals requires heavy investment in brand-new mining projects today.
China, fiercely committed to safeguarding its iron grip on global supply chains, has long been willing to allocate substantial capital to such long-term ventures. Japan has pursued a similar path, though out of necessity. Ever since China abruptly blocked exports of critical minerals to Tokyo amid a diplomatic dispute over the Senkaku Islands (known in China as the Diaoyo Islands) in 2010, Japan has been slowly and painfully disentangling its supply chains. Yet progress has been agonizingly slow. After 15 years of targeted investments, Japan has managed to reduce its dependence on China for rare earth elements from about 90 percent down to roughly 65 or 70 percent—a significant drop, but still nowhere near enough to supply its own domestic industrial needs, let alone assist its broader international allies.
Ultimately, investing in refining capacity is a necessary step, but it remains fundamentally insufficient. To truly insulate themselves from future supply chain weaponization, the United States and its allies, particularly within the Group of Seven (G-7), must urgently begin building a robust pipeline of new mines. These capital allocations are long-term bets fraught with substantial financial risk, but when successful, they yield extraordinary economic and strategic rewards.
THE VALLEY OF DEATH
Paradoxically, the United States and its Western allies significantly outperform China when it comes to early-stage mineral exploration. Exploration firms based in Australia and Canada alone account for roughly one-third of all global exploration spending. However, the vast majority of promising geological prospects never successfully transition into operating mines. This high attrition rate is rarely driven by a lack of initial financing for prospecting; rather, it is caused by the compounding financial disincentives and overwhelming risks that emerge the moment a mining project attempts to move forward into development.
The initial stages of mining development rely chiefly on a unique, highly specialized ecosystem of independent mining companies known across the industry as "juniors." These firms typically possess a small market capitalization, focus exclusively on one or a handful of specific projects, and are far too small to list on major stock exchanges. Most of them list their shares in Australia or Canada, concentrating their efforts exclusively on the high-risk exploration phase. The inherent geological uncertainty of prospecting makes betting on junior ventures extraordinarily speculative. Yet, if a newly discovered mineral deposit ultimately proves to possess significant reserves, the junior firm can either sell the project outright or bring in a major corporate partner, resulting in a massive financial payout.
Unfortunately, as projects progress to the subsequent stages, traditional investors routinely lose patience or exhaust their available capital. While initial prospecting is relatively inexpensive, the subsequent feasibility studies required to accurately estimate a deposit’s exact size, engineering needs, environmental compliance costs, and expected returns can easily run into the tens of millions of dollars. These costs come on top of expensive drilling, engineering, permitting, and comprehensive development planning.
Commercial lenders traditionally steer clear of these projects because they generate zero immediate revenue, offer no tangible assets to serve as collateral, and carry zero guarantees of eventual commercial viability. In short, the financial risk is simply too high to justify the uncertain returns. Meanwhile, major established mining companies routinely avoid these early-stage projects due to intense short-term pressure from shareholders to deliver immediate, maximum returns. Even as global demand for critical minerals has climbed dramatically, the share of corporate revenue that major mining companies reinvest back into new exploration and development has remained stubbornly flat.
Without access to outside financing, junior firms are completely unable to complete the rigorous technical studies required to attract subsequent rounds of construction funding, even when they have successfully identified a profoundly promising mineral deposit. As single-asset enterprises, they lack any other diversified cash flow or secondary assets to offer as collateral for additional commercial loans. This treacherous chasm in the financing lifecycle is widely known in the industry as the "valley of death."
Faced with a complete lack of Western backing, many cash-strapped companies looking for a way out of this predicament have turned to one remarkably reliable source of investment: China. Chinese state-backed and private entities have proven far more willing to absorb this specific type of high-stakes risk, providing the critical capital necessary to advance stalled mining projects. Consequently, they often represent the only viable option left for struggling junior firms. China’s towering dominance over global supply chains thus quietly relies on Western exploration companies. It endures not necessarily because China offers universally superior commercial terms, but because at the single most critical financing bottleneck in the entire industry, Beijing is effectively the only game in town.
DOWNSTREAM EFFECTS
China has spent decades methodically expanding its global supply pipeline for critical minerals through a combination of aggressive state-backed financing and strategic diplomacy. In 2025 alone, China spent a record $32 billion on metals and mining projects through its Belt and Road Initiative, breaking the previous year’s record of $21 billion. Chinese firms routinely demonstrate a unique willingness to invest directly in corporate equity, purchasing ownership stakes in foreign mining companies that come with no guaranteed short-term returns.
Additional Chinese spending frequently takes the form of sophisticated resources-for-infrastructure deals. Under this framework, Chinese state banks fund critical public infrastructure—such as deep-water ports, dedicated energy facilities, and heavy railways—in mineral-rich developing nations. In exchange, Chinese companies secure a direct share of the profits from local mining projects, which Chinese state banks often help finance directly. By investing in a sprawling, diversified portfolio of mineral projects scattered across multiple continents, Chinese firms can easily allow the immense profits generated by successful ventures to comfortably cover the inevitable losses of those that fail.
Beyond sheer capital deployment, perhaps the single most potent component of China’s comprehensive mining strategy is institutional know-how. Because failure is exceptionally common in mining, possessing the technical expertise to accurately identify geological deposits with the highest commercial potential is crucial. Beijing relies heavily on a coordinated network of specialized state-owned enterprises, dedicated geological survey firms, private companies, and seasoned government officials to meticulously vet projects, negotiate with foreign host governments, and secure necessary operational permits, infrastructure, and supply delivery routes.
Among the G-7 nations, the only country that maintains a comparable, active on-the-ground presence for global mining projects is Japan, which operates through targeted investments in nations such as Australia, Canada, Peru, and Uzbekistan. While these Japanese projects are deliberately designed to secure critical minerals for domestic industrial needs, they currently remain entirely insufficient to meet Japan’s own production requirements, let alone the broader, collective needs of its international allies.
The staggering disparity between China’s aggressive mining investments and those of the United States and its allies is perhaps most glaringly evident across the African continent, which holds some of the largest untapped mineral reserves on Earth. While the United States invested a modest $300 million or so in critical mineral projects across Africa in 2023, China pumped an estimated $8 billion to $10 billion into the region over the same period. Although Washington has formally recognized the urgent need to close this widening gap, U.S. policymakers still have a remarkably long way to go.
Consider the Democratic Republic of the Congo, a nation that became a primary focus of successive U.S. administrations due to its vast mineral wealth. Today, Chinese companies completely control roughly 70 percent of all copper and cobalt mines in the country. Between 2008 and 2020, Chinese banks and corporate entities extended well over $9 billion in direct credit to finance mine development and ongoing operations in the Congo, supplementing that with an additional $3 billion in infrastructure loans issued by the Export-Import Bank of China.
Crucially, the United States and other affluent G-7 nations had ample historical opportunities to participate in these lucrative investments, but repeatedly stepped aside after judging the projects to be excessively risky. In 2015, for instance, the Canadian-listed mining enterprise Ivanhoe Mines desperately sought Western funding for its massive Kamoa-Kakula copper project located in the Congo. With virtually no Western financial institutions willing to absorb the perceived political and operational risk, the Chinese mining giant Zijin Mining stepped in to acquire a major ownership stake. Today, Kamoa-Kakula is well on its way to becoming one of the single largest copper-producing mines anywhere in the world. Meanwhile, between 2016 and 2020, the only major American mining company active in the Congo quietly sold off its substantial equity stakes in two major copper-cobalt deposits—its final remaining operational holdings in the country—directly to a Chinese competitor.
In the global mining sector, the ultimate owners of a mine dictate precisely where its extracted minerals will eventually travel. When Chinese firms maintain outright ownership or controlling stakes in a foreign mine, the physical output is almost invariably routed directly to Chinese domestic refineries or downstream manufacturing facilities located within China. For example, the massive Chinese battery manufacturer CATL holds a direct ownership stake in the Kisanfu mine in the Congo, guaranteeing the firm a steady, uninterrupted supply of vital copper and cobalt for its electric vehicle batteries.
While certain U.S. automakers and allied battery producers have attempted to invest directly in select foreign mining projects, none have done so at a scale remotely comparable to Beijing. Even when Western firms manage to secure a stake, a substantial portion of that refined material still physically flows through Chinese processing hubs. This heavy geographic concentration of refined critical materials inside China grants Beijing ever-greater structural market power and the undeniable geopolitical leverage to weaponize those supply chains whenever diplomatic tensions flare.
MINING THE SOLUTION
In purely theoretical terms, the United States and its allies already possess the sophisticated financial markets and capital mechanisms necessary to fund their own robust pipeline of future mining projects. In 2024, two prominent Toronto-based stock exchanges hosted nearly 1,100 publicly listed mining companies, representing roughly 40 percent of the global total. These Canadian exchanges accounted for approximately one-third of all global mining equity capital raised over the preceding five-year period, with about half of the listed companies directing their projects toward Canadian soil. The Australian Stock Exchange serves as another powerhouse in the sector, hosting roughly 850 listed companies focused on mining development in 2024.
However, these publicly traded mining companies face severe market pressures that actively discourage investment in promising early-stage prospects. Because the world’s most accessible, low-hanging mineral deposits have already been thoroughly tapped, newly discovered deposits are increasingly located in complex, remote geological environments. This makes the crucial early stages of exploration significantly more difficult and vastly more expensive.
At the same time, moving a discovery from initial exploration to active commercial production is taking longer than ever before, largely because heightened social, environmental, and regulatory requirements have dramatically lengthened the permitting process. This elongated timeline severely depresses private investors’ appetite for risk, as they are forced to wait much longer for their invested capital to begin generating positive returns. Compounding these structural headwinds, aggressive industrial overproduction of critical minerals by China has artificially suppressed global market prices for key commodities. Despite overwhelming long-term market signals that global demand for these minerals will continue to skyrocket, these depressed spot prices actively discourage new market entrants and weaken the financial incentives for private investors to support companies already struggling to survive.
Consequently, U.S. and allied governments must step in to actively draw in substantial new institutional investment. The United States has initiated this effort by taking direct equity stakes in both domestic and international mining companies while expanding federal loan programs. While official government announcements frequently claim that these cumulative public investments total around $50 billion, the actual value of finalized binding deals signed to date is closer to $9 billion, with the amount of money physically moving into projects hovering near $4 billion. Crucially, the vast majority of this public capital bypasses the projects languishing in the treacherous valley of death. Instead, the ventures receiving federal funding are overwhelmingly those that are already closest to commercial production, as policymakers prioritize projects that can immediately mitigate short-term supply chain risks.
This federal push represents a positive start, but early-stage ventures that remain stranded in the exploration phase desperately require capital, and private institutional investors remain deeply wary of the sector. Since 2025, the few institutional investors that have engaged in mining finance have typically done so only after the U.S. government publicly announced an equity stake or federal loan to back the project. While this cautious approach is hardly new, relying entirely on government signals and public backing creates a perverse incentive for private enterprises to withhold their own capital in the complete absence of state support—precisely the outcome that governments are trying to avoid.
To genuinely unlock vast pools of private capital for grassroots exploration and mine development, the United States and the European Union would be wise to emulate Canada’s proven financial framework. The Canadian government offers targeted tax credits to companies actively engaged in mineral exploration, alongside a unique "flow-through shares" system that helps mining companies finance exploration and development by transferring valuable tax deductions directly to investors. If the broader G-7 can successfully establish a synchronized financial architecture modeled on this approach, vastly more exploration capital would naturally flow toward critical mineral projects. Furthermore, if member countries formally link their systems by allowing investors to claim tax benefits for exploration carried out anywhere across the G-7 territory, they could effectively construct a massive, shared pool of exploration and development capital capable of sustaining projects all the way through to physical construction. In addition, G-7 nations must actively remove persistent regulatory barriers that block large institutional investors—primarily pension funds, university endowments, and philanthropic foundations—from entering the mining sector. This requires urgent tax code reforms to eliminate rules that currently penalize tax-exempt institutional investors by taxing returns on mining investments as ordinary income.
Finally, in instances where private market incentives simply fail to align for specific high-priority projects, G-7 governments must deploy public capital directly to help mining companies escape the valley of death. To achieve this, the United States, Japan, and key European nations should establish a joint international financing facility specifically designed to pool capital for expensive feasibility studies, which remain notoriously difficult to fund through private markets. This facility would operate a diversified portfolio approach, ensuring that inevitable financial losses from failed projects are safely absorbed by the successes.
Such a pooled fund would allocate targeted grants to promising mineral projects in exchange for a direct equity stake in the venture or a guaranteed royalty once the mine successfully enters commercial production. While many individual projects would inevitably still fail, a dedicated, professionally staffed investment facility would drastically improve overall investment quality—mirroring the successful portfolio strategy long utilized by China in early-stage global mining. Ultimately, the long-term strategic and economic benefits delivered to both private investors and national security interests would far outweigh the initial capital lost on unsuccessful ventures.
Today, the most visible chokepoints for critical minerals are concentrated largely at the processing and refining stage. However, future strategic threats to the vital minerals required for advanced manufacturing, clean energy, artificial intelligence, and national defense technologies will originate directly at the mines. G-7 nations possess the robust markets and powerful policy tools necessary to build a secure pipeline of future mining projects and proactively prevent the next major economic emergency. Massive investments in downstream refining facilities will ultimately mean very little if the United States and its allies have no raw minerals to feed those refineries a decade from now. The only viable path forward is an immediate, coordinated commitment to financing the next generation of global mines.