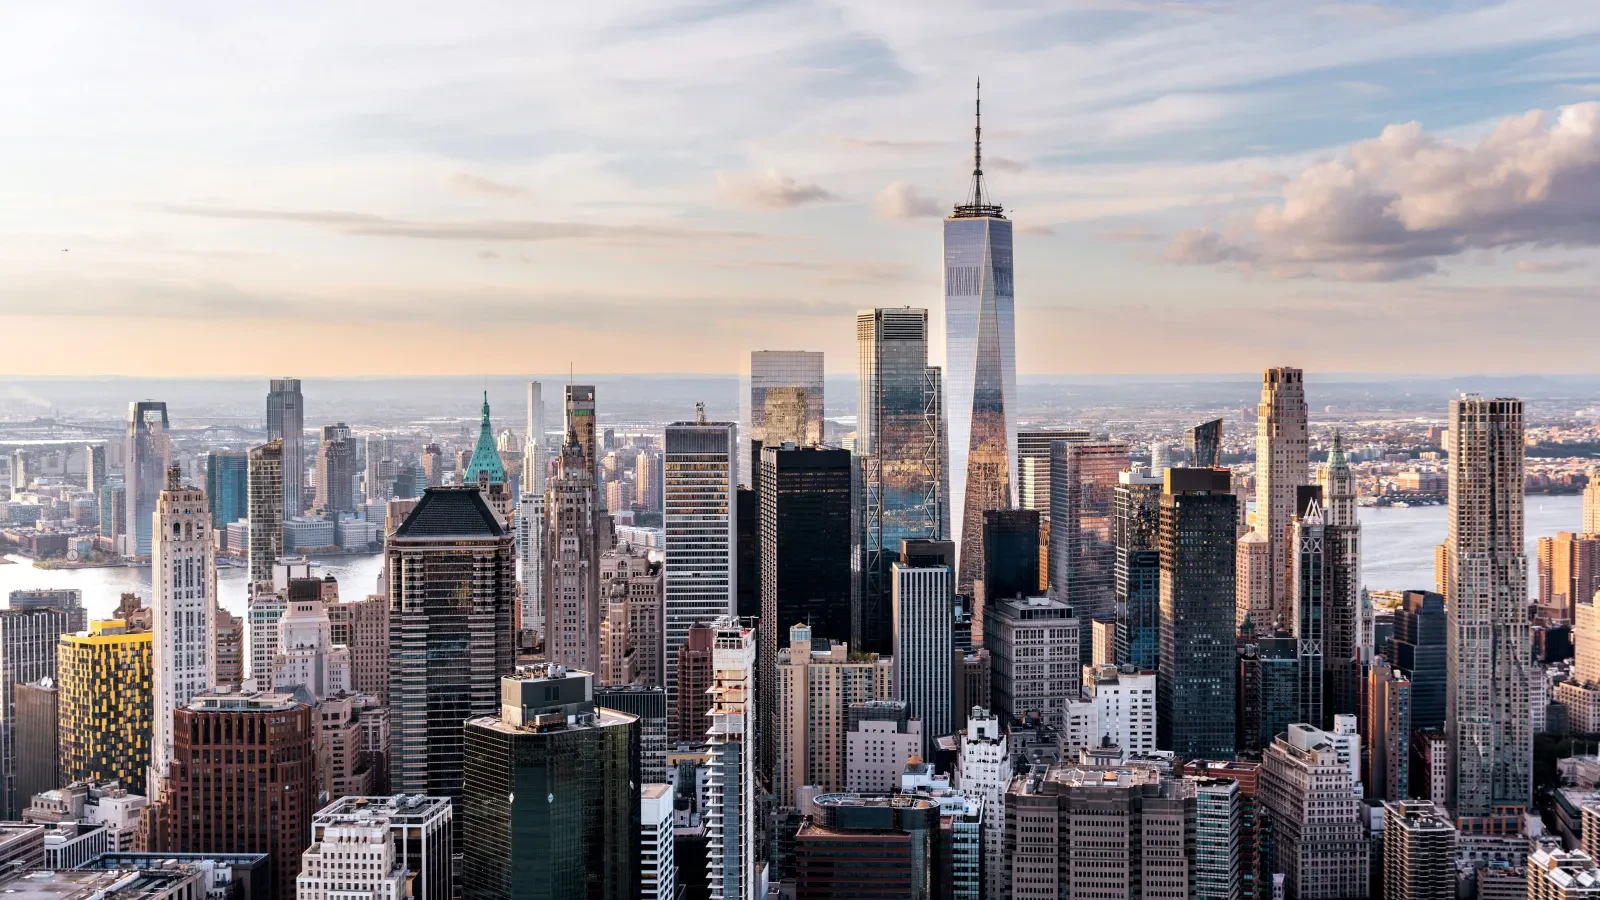
The judicial decision marks a major procedural victory for municipal officials as they attempt to implement the pied-à-terre tax, a policy designed to generate substantial revenue by targeting luxury secondary properties across the five boroughs. While the recent appeals court ruling cleared a major administrative hurdle regarding how the tax was rolled out, the broader policy continues to navigate a complex and uncertain legal landscape in state courts.
Dive Brief
The core of the recent appellate decision centered on the administrative mechanics of how New York City introduced the surcharge to the public. The rollout involved sending out approximately 17,000 mailed notices to property owners and publishing a massive database of 900,000 residences on the New York City Department of Finance website. The city referred to this expansive online registry as a "supplemental roll" of properties.
Plaintiffs, consisting of a small group of affected homeowners, had argued in lower courts that the initial wave of notices and the publication of properties on the municipal website were legally defective. They contended that the city’s notification strategy effectively shifted the burden of proof onto property owners, forcing individuals to independently determine whether their specific real estate holdings met the criteria for the newly minted tax. Furthermore, petitioners argued that the hurried and sweeping rollout generated widespread administrative confusion among residents and placed sensitive property data in a precarious position regarding public accessibility.
However, the state appeals court roundly rejected these arguments, concluding that the grievances raised by the homeowners did not rise to the level of legally actionable injuries. The reversal effectively breathes new life into the city’s implementation timeline, allowing municipal tax authorities to continue processing the surcharge without being forced to overhaul their initial notification procedures.

Dive Insight
The high-end second home tax is projected to have a sweeping impact on the luxury real estate market within New York City. Industry estimates and municipal projections indicate that the policy will ultimately affect roughly 13,000 secondary homes throughout the metropolis.
The financial threshold for the tax captures a broad swath of high-value real estate. It encompasses traditional one-, two-, and three-family residential homes valued at $5 million or more, alongside a massive inventory of condominiums and cooperative apartments valued at $1 million or more. For a city perpetually searching for new revenue streams to balance budgets and fund public services, the pied-à-terre tax represents a lucrative mechanism for tapping into accumulated luxury wealth.
Despite the financial potential for the city, the implementation process has been fraught with tension and legal friction. When the Department of Finance issued its 17,000 mailed notices and unveiled the supplemental roll containing nearly a million residences online, it immediately triggered a backlash from property owners who felt targeted and confused by the process.
The plaintiffs in the lawsuit argued that receiving a determination notice inherently penalized them by forcing them into a defensive posture. They maintained that the letters were vague and placed an unfair administrative burden on citizens to prove their primary residency status or valuation exemptions. They also voiced deep concerns over the publication of the supplemental roll, warning that making such extensive property data publicly available online created unnecessary risks regarding data privacy and the exposure of confidential records.
The appellate court, however, dismantled these arguments point by point. In its written opinion, the court of appeals clarified the legal definition of injury in the context of administrative notices.

"The mere receipt of the initial determination notices by [plaintiffs] does not qualify as an injury, in and of itself, as the notice instead serves an informational purpose," the court wrote. By framing the letters as standard informational correspondence rather than punitive or definitive legal judgments against specific titles, the court removed the foundational premise of the homeowners’ initial legal victory in the lower court.
Addressing the concerns regarding the publication of the supplemental roll and the potential compromise of confidential information, the appellate panel noted a critical lack of concrete evidence presented by the petitioners. The court pointed out that the plaintiffs "did not allege that any confidential material has been misused by the DOF as to cause a concrete harm."
Instead, the justices observed that the homeowners who had already submitted proper proof of residency were basing their legal grievances on speculative fears. Their stated harm amounted to little more than a generalized anxiety over the risk of an inadvertent public disclosure of confidential information at some unspecified point in the future. The court deemed this justification "too tenuous and conjectural to qualify as a concrete injury" capable of invalidating a municipal administrative action.
The court similarly dismissed arguments centered on the logistical friction accompanying the tax’s introduction. While petitioners argued vehemently that the rollout had created widespread and chaotic conditions for property owners navigating the new municipal requirements, the judiciary ruled that subjective confusion falls far short of legal harm. "Confusion has been held to be too generalized, tenuous, and ephemeral to constitute" an injury under the law, the court noted.
Even with this notable victory for the city regarding the mechanics of the rollout, the battle over the tax is far from over. Legal analysts and local media outlets, including reports by CNN, have confirmed that at least two other distinct legal challenges directly targeting the legality of the tax itself remain pending in the courts. While the recent appeals court ruling successfully defended how the city administered the notices and published the data, these separate ongoing lawsuits continue to threaten the long-term viability of the tax statute itself, leaving the ultimate fate of the surcharge hanging in the balance as judicial reviews proceed.
The debate in New York City is also part of a broader, national trend regarding property taxation and wealth equity. Municipal and state governments across the United States are increasingly looking at innovative ways to tax luxury real estate and non-primary residences as housing affordability crises grip urban centers and popular residential markets. Other states, including Montana and Rhode Island, are concurrently advancing their own legislative and administrative efforts to implement taxes on high-end, non-primary residences, mirroring New York’s aggressive stance on luxury property ownership.
As New York City digests this latest appellate decision, the Department of Finance can proceed with its administrative framework for the pied-à-terre tax, confident that its initial notification process has cleared judicial muster. Nevertheless, city officials remain acutely aware that until the remaining substantive lawsuits working their way through the court system are fully resolved, the high-end second home tax cannot be considered entirely secure. Property owners, tax attorneys, and municipal leaders alike will be watching closely as the remaining litigation unfolds in the months ahead.