Global fossil-fuel emissions are on track to decline by approximately 0.5% in 2026, driven largely by the profound economic and geopolitical fallout from the ongoing crisis in the Strait of Hormuz, according to a comprehensive new analysis by Carbon Brief.
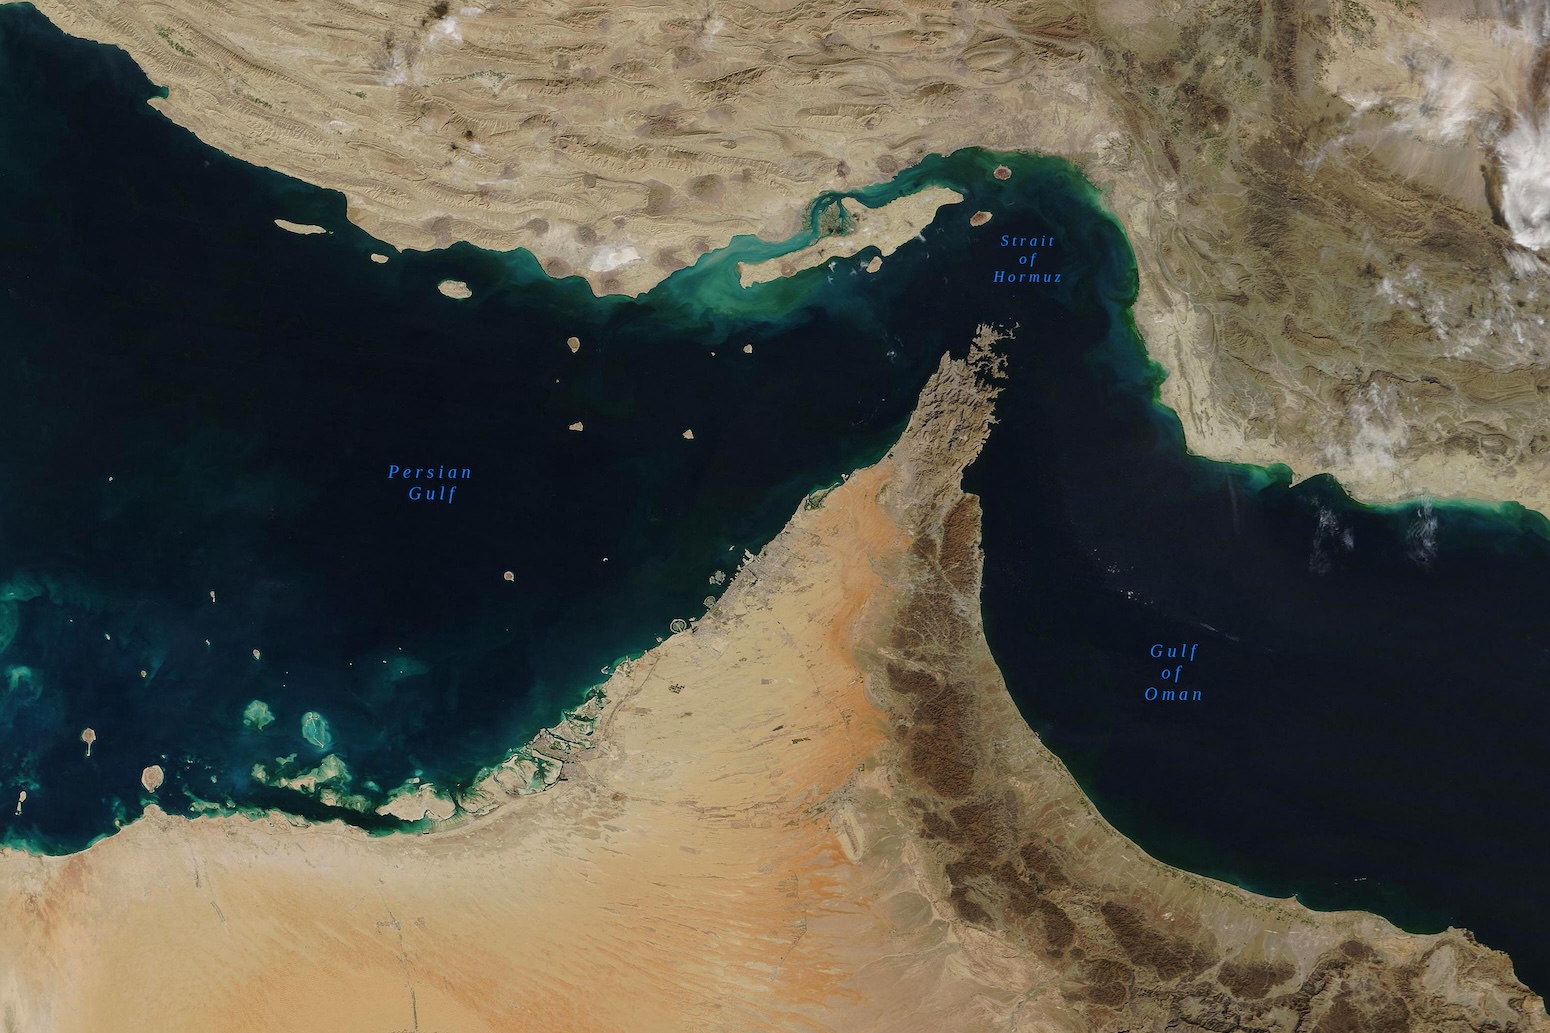
The prolonged conflict stemming from the US-Iran war has severely disrupted maritime trade and energy transit through the vital Strait of Hormuz. This disruption has triggered an immediate and volatile spike in global oil and gas prices, sending shockwaves that continue to ripple across the international economy. As energy markets grapple with instability, governments, industries, and consumers are forced to reevaluate their energy security, creating unprecedented structural shifts in how power and fuel are consumed worldwide.
Each successive month of disruption—compounded by related regional flashpoints, such as renewed violence in Yemen—is significantly intensifying the economic incentive to transition away from volatile hydrocarbons toward alternative energy sources.
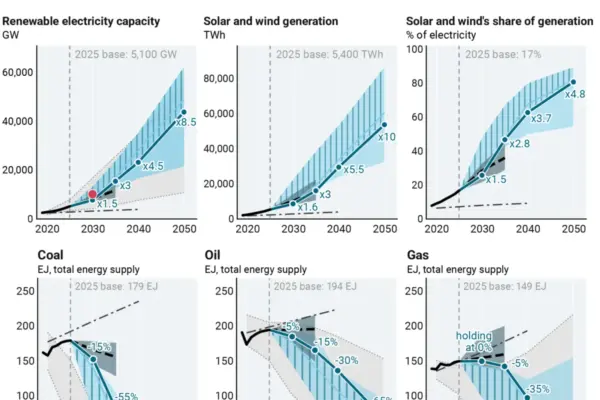
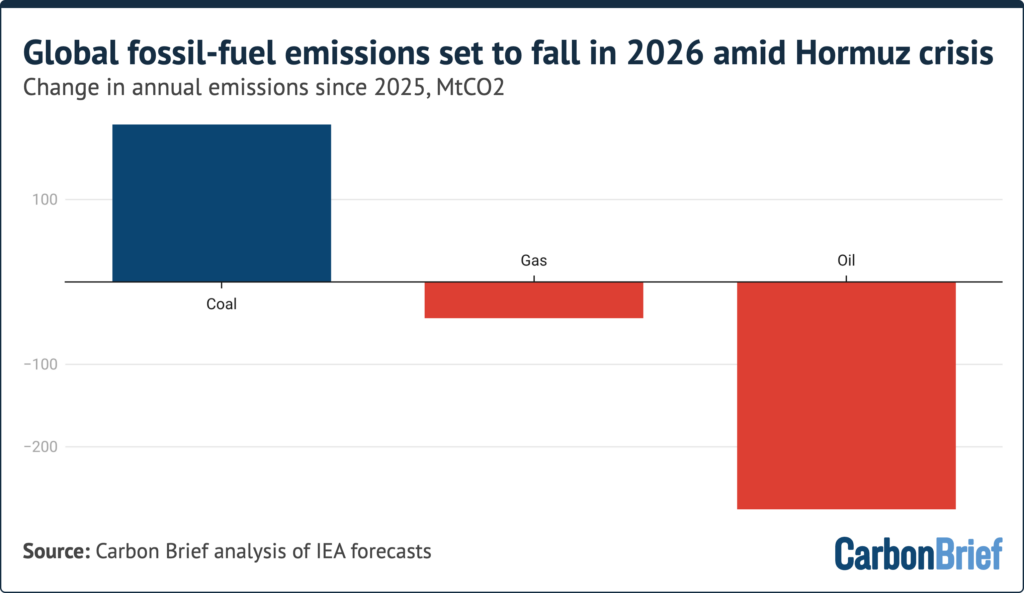
Amid these sweeping market changes, energy forecasters have noted a modest bump in coal demand. Latest projections point toward a 1.2% rise in global coal consumption this year, fueling media narratives and public discussions regarding a potential "return to coal" in the wake of the international energy crunch.
However, detailed data from Carbon Brief demonstrates that the marginal rise in emissions associated with this increased coal usage—much of which is driven by short-term factors completely unrelated to the events in Hormuz—will be far outweighed by sharp, substantial declines in both oil and gas consumption.
Consequently, the estimated net impact on global carbon dioxide (CO2) emissions from fossil fuels in 2026 translates to a reduction of around 0.5% compared to 2025 levels. To put this into perspective, fossil fuels historically account for roughly two-thirds of all global greenhouse gas emissions, making any systemic drop a notable deviation from historical growth trajectories.
The newly released emissions estimates for individual fossil fuels are derived from the latest, most up-to-date monthly and mid-year forecasts issued by the International Energy Agency (IEA), which has closely monitored the cascading effects of the ongoing global energy crisis on coal, oil, and gas markets.
The trajectory of these forecasts has shifted dramatically over the past year. Initially, the IEA anticipated that global coal demand would decline throughout 2026. In its 2025 coal report published in mid-December, the agency projected that falling coal demand within China would successfully offset the impact of pro-coal policy agendas championed by US President Donald Trump.
In sharp contrast, the IEA’s revised mid-year update, published in September 2026, revealed that global coal demand is now expected to expand by 1.2% over the course of the year, reversing expectations of a small demand contraction.
The agency’s report highlighted that higher natural gas prices resulting from the Hormuz crisis have provided a temporary economic boost to coal use as power generators seek cheaper alternatives. Nevertheless, analysts emphasize that there are strict technical and logistical limits to this trend, as relatively few countries possess the infrastructure required to switch rapidly from gas to coal on a large scale.
Furthermore, the IEA’s updated assessment points to a confluence of other short-term factors influencing coal demand this year. A particularly strong El Niño weather pattern has driven up electricity demand for cooling purposes while simultaneously depressing hydropower generation in several key regional markets. Additional localized factors, such as rising levels of curtailed or "wasted" wind and solar energy output in China, have also temporarily altered fuel dispatch dynamics.
The outlook for natural gas has undergone a similarly distinct pivot. At the beginning of 2026, the IEA maintained a forecast that global gas demand would grow by 2.0%, based on projections published in January. By July, however, updated data pointed to an anticipated 0.6% contraction in gas demand for the year. Since that time, intense upward pressure on consumer and industrial gas prices—exacerbated by supply constraints—has only grown stronger, dampening consumption across major importing regions.
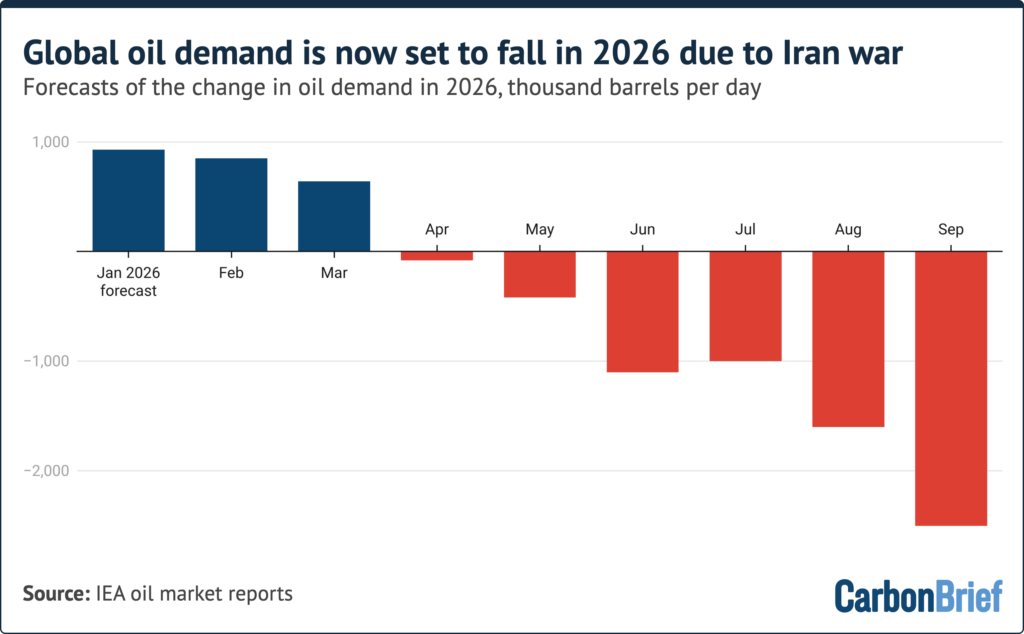
When examining oil markets, the shift in forecasts since the turn of the year has been even more dramatic. In its January 2026 oil market report, the IEA initially forecasted a modest demand growth of 930,000 barrels per day (bpd) for the year. As the Hormuz crisis ignited and subsequently extended into a prolonged standoff, that projection was steadily and aggressively revised downward month after month.
By September, the IEA’s outlook projected a staggering 2,500,000 bpd drop in global oil demand for 2026, representing an overall reduction of 2.4% relative to 2025 baseline levels. Independent financial institutions have echoed these findings; a research note published on September 15 by Morgan Stanley pointed to an industry consensus forecasting a demand drop of approximately 2,415,000 bpd for the year.
While these shifting short-term forecasts are influenced by a complex web of immediate market conditions, energy experts indicate that the current crisis will leave a lasting imprint on fossil-fuel demand well into 2027 and beyond.
Earlier in the year, the IEA initially anticipated that global oil demand would experience a robust rebound in 2027, pushing consumption well past 2025 highs. Today, the agency expects oil use to remain effectively flat for two consecutive years. This stagnation casts significant doubt on previous long-term expectations—such as those published in late 2025—which suggested that global oil demand might not peak until close to 2030.
"For every month the conflict lasts, the probability of permanent [oil] demand destruction increases," noted Sverre Alvik, vice president at energy consultancy DNV, in an analysis published in late August.
As international fuel and petroleum prices have surged to historic highs, electric vehicles (EVs) have successfully captured record market shares across major automotive regions. From Australia and China to key European markets, Indonesia, and Thailand, consumers are accelerating their pivot away from internal combustion engines. Alvik highlighted that in July alone, EV sales nearly doubled year-on-year across emerging "new markets" located outside of the traditional strongholds of China, Europe, and North America.
Looking ahead, the IEA notes that the 2027 outlooks for coal and gas remain deeply interdependent. Coal demand could experience renewed growth if natural gas prices remain elevated, or alternatively, retreat if gas markets manage to stabilize.
Concurrently, governments in developing nations that had previously structured their long-term energy security around imports of liquefied natural gas (LNG) are signaling strategic policy shifts. Faced with exorbitant import bills, these nations are increasingly looking to accelerate the deployment of domestic clean energy sources, or in some cases, contemplate extending the operational lifespan of existing coal-fired infrastructure.
Ultimately, the compounding pressures of the current geopolitical crisis carry the distinct potential to depress fossil-fuel use and associated carbon emissions not only as a temporary, acute shock, but also on a permanent, structural basis over the long term.