For nearly 40 years, John Steinbach has called his Manassas, Virginia, home a place of steady comfort. But in January 2026, that comfort was tested when he opened an electricity bill totaling $281—a sharp jump from roughly $100 the month prior. Speaking with Consumer Reports, Steinbach noted that the figure was far beyond anything he had ever experienced. What worries him and millions of other residents isn’t just the single spike, but the trajectory of local utility rates as a growing fleet of artificial intelligence data centers plugs into the regional power grid.
Steinbach is far from alone in his anxiety. A Gallup poll conducted in March 2026 revealed that seven in 10 Americans oppose the construction of AI data centers in their local communities, with nearly half—48%—strongly opposed. Intriguingly, this backlash transcends traditional political boundaries, drawing substantial majorities of disapproval from Democrats, Republicans, and independents alike.
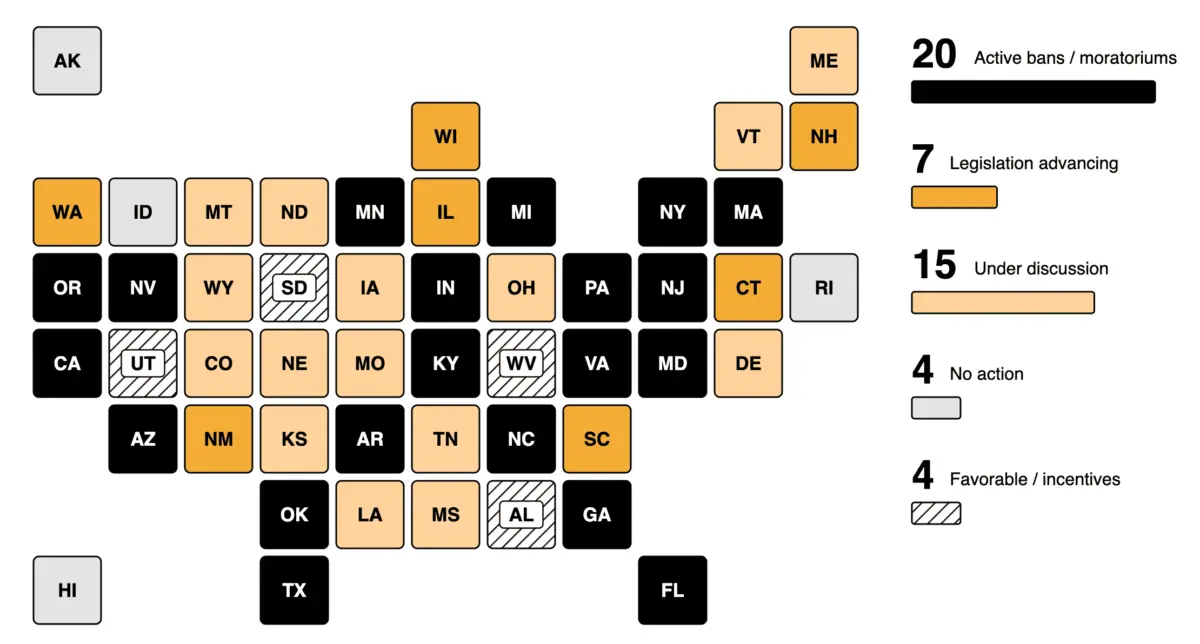
This widespread grassroots opposition has rapidly transformed into tangible policy roadblocks. According to tracking data from Data Center Watch, local pushback disrupted approximately 120 projects during the first half of 2026 alone. At least 45 of those developments, representing an estimated $68 billion in capital investment, stalled out during the second quarter. Across the United States, roughly 379 jurisdictions have enacted moratoriums or outright bans on data center construction.
Municipalities are moving swiftly to put the brakes on unchecked development. In August, the Indianapolis City Council voted 23–1 to halt new data center construction through 2027. Similarly, Charlotte implemented a 150-day moratorium on new approvals following a municipal survey that showed 78% of residents opposed such projects. According to Brookings, political candidates across the country and from both major parties are increasingly running campaign advertisements targeting the facilities.
Public debates are typically framed around a binary choice: whether or not data centers should be built at all. However, a much more complex and contentious question underlies the entire movement: who pays, and who decides? The costs of these massive facilities tend to land locally and immediately, while the economic benefits often materialize regionally or nationally at a much later date. Compounding the issue, the regulatory rules governing how these costs and benefits are split were written long before the advent of AI-scale electricity and water demand.
Why AI Changed the Math
To understand the current friction, it is necessary to examine how computational demands have evolved. Traditional cloud computing data centers were designed around general-purpose servers whose power loads rise and fall dynamically with user traffic. In contrast, modern AI clusters pack specialized graphics processing units much more densely, generating significantly higher heat per rack. During intensive training runs, these clusters draw immense amounts of power around the clock, fundamentally altering what a single corporate campus demands from local electrical grids and water systems.
Data centers across the United States consumed approximately 176 terawatt-hours of electricity in 2023, representing roughly 4.4% of the nation’s total power consumption, according to a Lawrence Berkeley National Laboratory report prepared for the Department of Energy. The central point of contention, however, lies in the unprecedented growth projected for the near future.
A comprehensive power report published by Bloom Energy in January 2026 projected that U.S. data center IT loads will nearly double, climbing from approximately 80 gigawatts in 2025 to roughly 150 gigawatts by 2028. While Bloom Energy manufactures on-site power systems and has a commercial stake in the outcome, the projections highlight a very real infrastructural bottleneck. Utility companies currently expect to deliver required grid power 1.5 to 2 years later than developers’ timelines demand. Consequently, developers now anticipate that roughly a third of all new data centers will run entirely on on-site power generation by 2030, effectively bypassing traditional utilities when the public grid cannot keep pace.
Electricity Bills: Who Pays for the Next Grid
Public concern frequently centers on regional wholesale electricity markets. PJM Interconnection, the regional transmission organization serving 13 states and Washington, D.C., operates capacity auctions designed to pay power plants to remain available during peak demand periods.
The financial shifts in these auctions have been dramatic. The clearing price for PJM capacity rose from $28.92 per megawatt-day for the 2024–2025 period to $269.92 for 2025–2026. Subsequent auctions hit the regulatory price cap, clearing at $329.17 and $333.44. PJM’s independent market monitor attributed 63% of the 2025–2026 price increase—amounting to roughly $9.3 billion—directly to rising data center load.
Other indicators point toward similar pressures. Federal Energy Information Administration data shows residential electricity prices in Virginia rose by about 13% over a 12-month period. A January 2026 survey conducted by Global Strategy Group and the Chesapeake Climate Action Network Action Fund found that nearly three-quarters of Virginia voters blamed data centers for the upward drift in their utility costs.
Looking further ahead, a peer-reviewed modeling study conducted by researchers from NC State, Carnegie Mellon, and other institutions projects that wholesale electricity prices will be 6% to 29% higher nationally by 2030 compared to a baseline without data center growth, with increases reaching up to 57% in the hardest-hit regions. It is worth noting that these figures represent wholesale market prices rather than direct retail utility bills.
Conversely, the technology industry argues that large, stable corporate customers frequently help lower overall rates. An Electric Power Research Institute study examining the years 2015 through 2024 found that each doubling of data center capacity correlated with average retail prices that were 3.5% lower. The logic is that large, continuous industrial loads allow utilities to spread their fixed infrastructural costs across a much broader base of energy sales.

An Amazon-funded study conducted by the energy consultancy E3 concluded that Amazon’s utility payments in four distinct service territories met or exceeded the actual cost of serving its facilities, leaving an average net surplus of about $3.4 million per site. A separate E3 report commissioned by the Data Center Coalition estimated that load growth accounted for roughly 50% of the 2025–2026 PJM price increase, a figure notably lower than the independent market monitor’s estimate. Furthermore, the free-market Institute for Energy Research found no statistically significant correlation between a state’s total number of data centers and its average electricity prices.
Empirical policy research suggests the financial impact is complex. The Rutgers New Jersey State Policy Lab found no statistically significant effect on utility-level residential bills through 2024, though researchers cautioned that "not yet" is not synonymous with "nothing to worry about." Historical benefits depended heavily on spare capacity within existing electrical grids. If new infrastructure is built to accommodate projected demand that ultimately fails to materialize, the fixed costs of those capacity expansions will inevitably be distributed among a smaller pool of ratepayers. With transmission and distribution spending already climbing across the country to modernize aging grids, the critical policy question is no longer whether data centers have spiked bills in the past, but rather who will foot the bill for the next wave of inevitable grid expansion.
Water: National Totals, Local Stress
Water consumption represents another major flashpoint. Water-cooled data centers can easily consume millions of gallons on a single hot summer day, putting severe localized pressure on arid regions. Arizona, for instance, faces a federal mandate to cut its Colorado River water usage by 760,000 acre-feet—a reduction of roughly 27% to 30%.
This environmental backdrop heavily influences municipal decisions. The Tucson City Council unanimously rejected Amazon’s proposed Project Blue in August 2025, and officials in Chandler subsequently voted down a separate AI data center proposal 7–0 that December. In Florida, the Orange County vice mayor proposed a one-year moratorium on new facilities, pointing to a projected regional groundwater shortfall of 96 million gallons per day by 2045.
While viral estimates suggest that a typical 100-word AI prompt consumes about half a liter of water—a figure derived from early UC Riverside research regarding GPT-4—Google’s published data for a median Gemini text prompt indicates a consumption rate of roughly 0.26 milliliters, or about five drops, though that figure accounts strictly for on-site evaporation.
At a macro level, Lawrence Berkeley National Laboratory estimates that U.S. data centers directly consumed about 17.5 billion gallons of water in 2023, a total that could easily double or quadruple by 2028. Defenders of the industry often note that this represents a fraction of total national consumption; economist Jim Pethokoukis has noted that data centers account for less than 0.5% of total U.S. freshwater use, comparing the consumption of a major Google facility in Iowa to that of a typical golf course. An Arizona State University report similarly found no measurable rise in central Arizona municipal water use attributable to data center growth, noting that regional agriculture continues to account for roughly 72% of the state’s total water consumption.
However, national averages obscure intense localized stress. In Botetourt County, Virginia, a planned Google campus could consume between 2 million and 8 million gallons of water daily in a rural county where many households rely on private wells. To accommodate the facility, the local government is committing $300 million toward a new regional water supply, funded in part by anticipated tax revenues from the project.
Jobs and Tax Revenue: A Strong Case and a Thin One
The economic development argument remains the tech industry’s most potent defense. Data centers across Northern Virginia generated an estimated $1.3 billion in local property taxes in 2024, with total supported local revenues topping $2 billion, according to the Chamber of Progress.
Quincy, Washington, is frequently cited as a success story for municipal partnerships. In that small agricultural community, approximately 30 data centers account for an estimated 57% of the local property tax base. This substantial revenue stream has helped fund a $120 million high school, a local hospital, new police and fire stations, and a $30 million water reuse facility built in partnership with Microsoft.
In Texas, industry data cited by the Texas Tribune claimed that data centers supported 61,060 direct jobs and contributed $3.5 billion in state and local taxes in 2023. Company representatives have argued that a single proposed $10 billion campus would inject $50 million annually into Lacy Lakeview, a town of approximately 7,000 residents. Legislative auditors in Virginia even ranked the state’s data center tax exemption as its second-most productive economic incentive, generating $6.1 million in personal income for every $1 of forgone state revenue.
By contrast, the direct job creation argument is considerably more modest. A Brookings Institution analysis examining roughly 1,500 facilities found that the arrival of a county’s first large data center typically creates between 100 and 200 jobs over a decade, with no measurable impact on local wage levels. State incentive thresholds often reflect this reality; Texas grants sales tax exemptions to facilities spanning at least 100,000 square feet that create 20 jobs, while Maryland requires just five jobs and a $2 million investment in targeted areas. While construction employment numbers are substantial, those jobs are temporary.
In response to these mixed economic returns, state capitals are recalibrating their incentive structures. Governors in Illinois, Massachusetts, Nebraska, Nevada, and Ohio have paused or revised tax breaks over the past year, and Arizona temporarily froze new awards for three years. Meanwhile, Virginia preserved its foundational tax exemption but instituted a temporary electricity tax of 1.1 cents per kilowatt-hour on data centers, running through June 2028 and capped at $600 million annually.
Air Pollution and On-Site Power: The Memphis Case
Memphis serves as an extreme outlier, yet it illustrates the environmental friction that occurs when companies bypass traditional utility connections. To bring its Colossus 1 supercomputer online in 2024, xAI operated trailer-mounted methane gas turbines in South Memphis—numbering as many as 35 according to aerial imaging by the Southern Environmental Law Center—near Boxtown, a neighborhood already burdened by decades of heavy industrial pollution. For its subsequent Colossus 2 project, the company placed turbines just across the state line in Southaven, Mississippi, operating 46 units by May 2026.
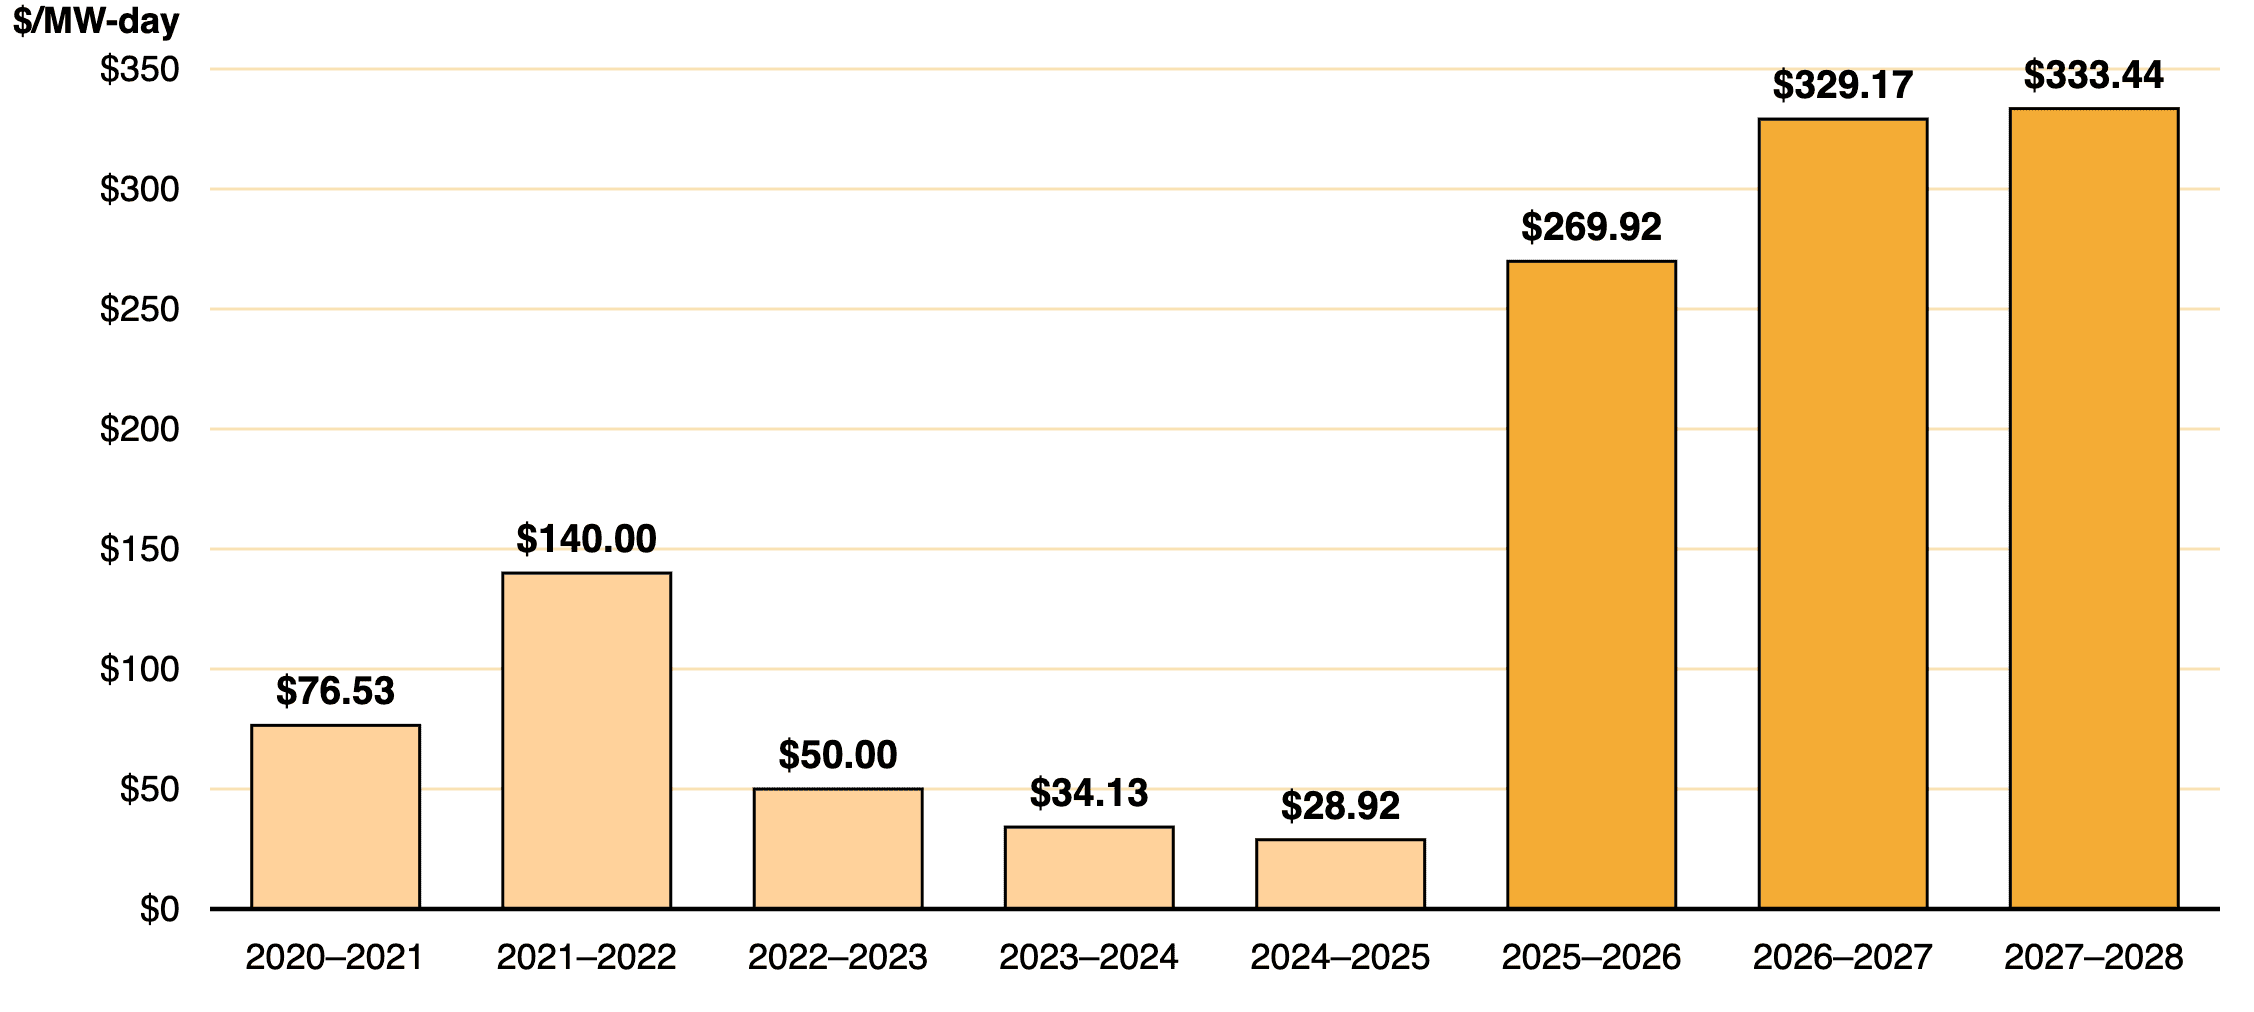
Initially, classifying these mobile units as "non-road engines" allowed xAI to avoid standard air permitting requirements until an Environmental Protection Agency rule change in January 2026 clarified that large stationary turbines require formal permits. SpaceX, which acquired xAI, subsequently operated 69 turbines and indicated that unpermitted units would not be fully removed until July 2027 while a permanent 1.2-gigawatt gas plant is constructed. Legal battles have followed, with the NAACP, represented by the Southern Environmental Law Center and Earthjustice, filing lawsuits under the Clean Air Act.
The federal government has intervened on the corporate side; in June, the Department of Justice filed arguments supporting xAI, characterizing the unpermitted turbines as a matter of "national, economic, and energy security." Third-party air quality testing commissioned during the dispute found that ten measured pollutants remained below dangerous thresholds, though environmental advocates noted that ozone was not included in the panels and that prevailing winds blew away from monitoring stations on testing days.
Independent academic studies have yielded mixed conclusions. An analysis of satellite data conducted by the University of Tennessee, Knoxville for TIME found that average nitrogen dioxide levels rose by approximately 3% after June 2024, with peak concentrations spiking by up to 79% directly around the site and 9% in Boxtown. Conversely, University of Memphis researchers modeling local air quality calculated a roughly 1% increase in fine particulate matter while detecting no statistically significant shift in broad satellite datasets, though they acknowledged their models could not track several hazardous chemical compounds.
While the average environmental impacts across a broader geographic area may appear modest, they are concentrated in neighborhoods already experiencing heavy industrial pollution, operating without the formal permitting processes designed to evaluate such risks. More commonly, however, the workaround is quieter: proposed campuses like Aurora, Colorado’s Trident facility plan to rely on dozens of heavy diesel backup generators.
Local Control and the Risk of Speculative Demand
A significant driver of the public backlash centers on governance and transparency. Before Applied Digital’s $3.6 billion Louisiana campus was publicly announced as Delta Forge 1, it was developed under code names such as "Project Lightning" and "Project Pixel" via nondisclosure agreements signed by state senators, local assessors, and members of approving boards. In response, lawmakers in states like Michigan, Oklahoma, Kentucky, and Ohio have introduced legislation to ban such secrecy agreements, and Pennsylvania Governor Josh Shapiro has barred state agencies from entering into them.
Zoning laws can similarly bypass public debate. In Aurora, Vantage’s roughly 500-megawatt Trident campus can be approved administratively without public hearings because the underlying zoning already permits data centers, despite sitting directly across from residential neighborhoods and demanding power equivalent to eleven times that of the Denver International Airport.
When local governments attempt to push back, developers frequently test their legal boundaries. Hill County, Texas, passed a moratorium in May 2026 only to rescind it two weeks later after a developer filed a lawsuit seeking more than $100 million in damages. The county ultimately replaced the ban with a compliance checklist requiring developers to report projected water usage, traffic, noise, and economic impacts. Other jurisdictions have stood their ground; Inver Grove Heights, Minnesota, enacted a moratorium in June despite threats of legal action from developers.
At the state level, executive and legislative branches are increasingly stepping in. Texas Governor Greg Abbott ordered an audit of all data centers seeking grid connections and subsequently halted state permitting for new facilities pending the audit’s completion. According to the Rockefeller Institute, 14 states considered moratorium legislation as the policy landscape continued to shift.
Underlying these regulatory battles is a fundamental economic uncertainty shared by both critics and boosters: the assumption that projected AI demand will materialize precisely as forecasted. McKinsey’s widely cited projections estimate global data center capital spending at roughly $6.7 trillion by 2030, and both the tech industry and its opponents frequently treat that expansion as an absolute certainty.
Should that demand fall short, however, the financial liabilities will remain. Utility companies that construct multi-billion-dollar generation and transmission facilities for projects that are subsequently downsized or canceled must still recover those capital expenditures from remaining ratepayers. This reality has pushed minimum capacity payment requirements and strict exit terms to the forefront of utility regulation. In Virginia, state regulators already require the largest industrial customers to pay for at least 85% of their contracted transmission and distribution demand and 60% of generation demand, regardless of whether they consume that electricity.
Ultimately, the most rigorous empirical studies and local policy debates point to a central imbalance: the financial and environmental costs of modern data centers are predominantly local and immediate, while their economic benefits are largely regional or national and arrive much later. As statehouses and municipal councils continue to draft new regulatory frameworks, the defining question for residents watching new projects break ground nearby remains simple: if the projected digital demand never fully arrives, who will ultimately pay for the grid?