For many consumers tracking the ever-shifting landscape of travel rewards, the Bilt Rewards program is often dismissed out of hand by those who do not hold its flagship credit card. Conventional wisdom suggests that unlocking the lucrative ecosystem of Bilt Points requires an application for the brand’s specific plastic. However, a growing number of savvy travelers are discovering that it is entirely possible to generate a steady stream of Bilt Points each month without ever opening a Bilt credit card. By strategically combining routine monthly expenditures—most notably rent and rideshare services—with linked external payment methods, consumers can tap into the program’s valuable transfer partners and accumulate significant rewards balances over time.
While holding a Bilt credit card remains the standard path for many, the program’s underlying architecture allows non-cardholders to participate under specific conditions. For renters whose apartment complexes participate in the Bilt network, the opportunity to earn points on housing payments exists independently of the card portfolio. Setting up a basic Bilt account is the first prerequisite, followed by a careful consultation with the local leasing office. Because participating residential complexes retain the autonomy to decide whether they will accept external credit cards through the platform or restrict transactions exclusively to Bilt-branded cards, verifying property policies is a crucial preliminary step.
The mechanics of earning rewards without the Bilt card depend heavily on the payment options displayed within an individual’s digital Bilt dashboard. When a leasing office permits the use of standard credit cards routed through the Bilt platform, users can securely link their preferred external cards to establish automated monthly payments. Under this framework, cardholders earn 1 Bilt Point for every $2 spent on rent. Crucially, these Bilt rewards accumulate on top of whatever standard earnings the linked credit card normally provides for everyday or non-bonus spending categories.
This dual-earning potential comes with a notable caveat: transactions processed this way typically incur a standard 3% processing fee. For many reward enthusiasts, however, this fee is viewed as a manageable cost of doing business, particularly when the massive monthly expenditure of rent is directed toward fulfilling spending thresholds required for lucrative credit card welcome bonuses. For instance, a monthly rent payment of $2,000 generates a $60 transaction fee. Whether incurring that fee is financially sensible depends entirely on the intrinsic value of the welcome offer being pursued or the strategic utility of the transferred points. Furthermore, because mortgage payments cannot currently be processed through Bilt without utilizing a Bilt credit card, this workaround remains strictly limited to renters.
Beyond the realm of housing, consumers can effortlessly pad their balances by integrating other daily routines into the ecosystem. Individuals who frequently utilize rideshare services can link their Bilt and Lyft profiles to automatically generate 2 points per dollar spent on rides. This accumulation stacks directly on top of whatever rewards the user’s personal credit card yields for transportation spending. Premium travel cards, such as the Chase Sapphire Reserve, can elevate these returns significantly, allowing users to harvest multiple layers of rewards from a single transit transaction.
One of the most compelling aspects of participating in the Bilt ecosystem without its dedicated credit card is the unrestricted access to the program’s roster of airline and loyalty transfer partners. In an industry where major issuers frequently gatekeep their best redemption opportunities behind premium proprietary cards, Bilt allows all account holders to transfer their balances to participating programs. This openness provides an invaluable bridge to carriers that might otherwise be difficult to access for certain travelers.
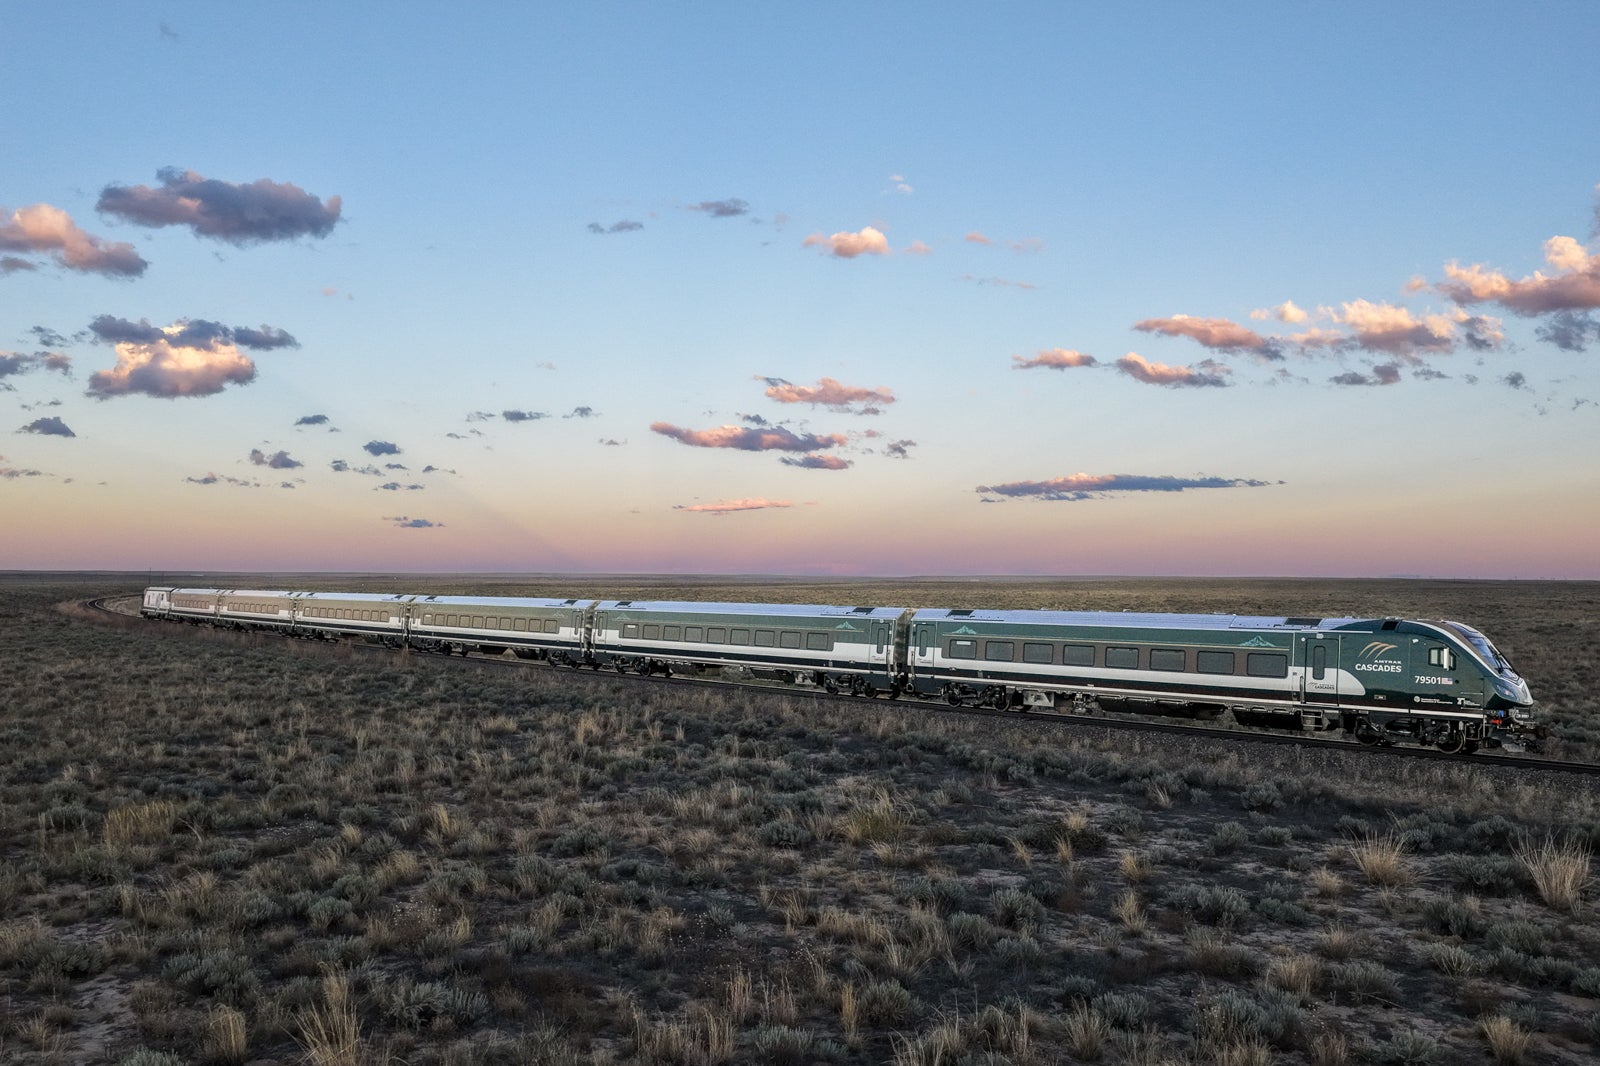
Bilt’s transfer network includes prominent international and domestic loyalty programs such as Air Canada Aeroplan, Southwest Airlines Rapid Rewards, and Virgin Atlantic Flying Club. More recently, the inclusion of Amtrak Guest Rewards as a transfer partner has opened new avenues for travelers who rely on rail transit for regional travel along major corridors. While members holding base Blue Status—the typical tier for non-cardholders—must adhere to a minimum transfer threshold of 2,000 points per transaction compared to the lower thresholds afforded to elite tiers, the underlying transfer capability remains fully intact. All point transfers within the ecosystem remain strictly irreversible, demanding careful planning before executing a move.
The tangible benefits of this strategy are underscored by real-world redemptions executed by program participants. Travelers have successfully transferred modest point balances to top off accounts for regional domestic itineraries, transforming monthly housing overhead into free flights that would have otherwise required substantial out-of-pocket cash expenditures. When factoring in minimal taxes and carrier-imposed fees, the realized value per point on short-haul redemptions can easily exceed standard valuations, turning routine living expenses into high-yield travel opportunities.
While generating points without a dedicated Bilt card happens at a slower pace compared to active cardholders, consistent monthly rent payments and transit linkages can yield a respectable sum over time. For individuals who generate several hundred points each month from housing, the cumulative balance quickly transforms into enough currency for short-haul domestic getaways once transferred to partner airlines.
Choosing the appropriate external credit card to route through the Bilt platform requires careful financial calculation. Cardholders currently tackling a high-minimum welcome offer can leverage their rent to accelerate progress toward the bonus, keeping in mind that the 3% processing fee will marginally diminish the net value of the reward. Alternatively, consumers not pursuing a specific welcome bonus should evaluate cards that offer spending milestones, such as annual travel credits unlocked after hitting specific yearly expenditure thresholds.
Because rent payments coded through Bilt attract standard credit card rewards, utilizing a card that yields higher than average returns on general spending is vital. Products such as the Capital One Venture X Rewards Credit Card and the Citi Double Cash Card provide competitive baseline returns on non-category purchases, maximizing the yield on every dollar allocated toward housing. Meanwhile, targeted cobranded products, such as the Air France KLM Visa Signature credit card, offer elevated earning rates specifically for rent transactions processed through the Bilt platform up to annual caps.
Conversely, consumers who find themselves consistently paying rent at properties that reject external cards, or those who wish to avoid transaction fees entirely while maximizing point accumulation on housing, may eventually find that applying for a Bilt credit card aligns more closely with their financial strategy. The current portfolio of Bilt cards caters directly to these specialized housing needs, offering alternatives for renters and homeowners alike.
Ultimately, participating in Bilt Rewards does not require a binding commitment to the program’s credit cards. For renters living in compatible properties willing to navigate transaction fees strategically, the platform serves as an effective mechanism to harvest transferable points from unavoidable living expenses. By bridging everyday spending habits with a diverse portfolio of airline and rail transfer partners, budget-conscious travelers can extract significant value from their largest monthly liabilities without altering their wallet composition.